Why does a commodity trader need a commodity-aware CTRM, not a generic ERP module?
A generic ERP inventory module tracks quantity and average cost, treating a tonne of copper the same as a finished good on a shelf. A commodity trader needs a system that tracks price exposure separately from ownership: index and differential pricing, un-fixed contracts, quality adjustments, hedge exposure, laytime, and letter of credit workability. The CTRM and ETRM vendor market itself is expanding from energy and metals into softs and agri, which is a sign of where the baseline is moving.
By Saurabh Goyal, Founder & CEO of Phlo Systems. Published 5 October 2026.
Most generalist ERP vendors treat a tonne of copper, a bushel of wheat, and a litre of diesel the same way: a stock-keeping unit with a quantity, a unit cost, and a warehouse location. That model works well for a manufacturer moving finished goods through a bill of materials. It breaks down quickly for a company whose core business is the commodity itself, because the inventory module was never built to answer the questions a trading desk actually asks: what is this position worth if the index moves a dollar, what basis am I carrying against the futures month, and is this lot even priced yet.
The 30-second answer: a generic ERP inventory module tracks quantity and average cost. A commodity trader needs a system that also tracks price exposure separately from ownership, because a lot of physical stock and the financial position tied to it are not the same thing and often move independently. That means index and differential pricing, un-fixed and provisionally-priced contracts, grade and quality specifications that affect value, hedge and VaR exposure by commodity, and laytime, freight, and letter-of-credit workability built into the transaction, not bolted on afterward. Competitive research across the CTRM and ETRM market shows generalist platforms expanding outward from their traditional energy and metals base into softs and agricultural commodities such as dairy and grain, which is itself evidence that commodity-specific functionality is becoming a baseline expectation rather than a specialist add-on.
Why "inventory" is the wrong model for a trading position
A generic ERP's inventory module answers one question well: how much of something do I have, and what did it cost me. For a distributor or a manufacturer, cost and value move together closely enough that average or standard costing is a reasonable approximation of economic reality.
A commodity trader's stock does not behave that way. The firm can own a cargo of soybeans outright while having already sold the price risk on it through a futures hedge, so the inventory module's "cost" tells the finance team almost nothing about what that cargo is actually worth to the business today. Ownership of the physical goods and exposure to their price are two different things that a trading book has to track separately, and a system built around a single quantity-and-cost record cannot do that without a parallel spreadsheet sitting next to it.
What a commodity-aware CTRM tracks that a generic ERP does not
Six gaps show up repeatedly when a trading firm tries to run its book on a general-purpose ERP module built for manufacturing or distribution.
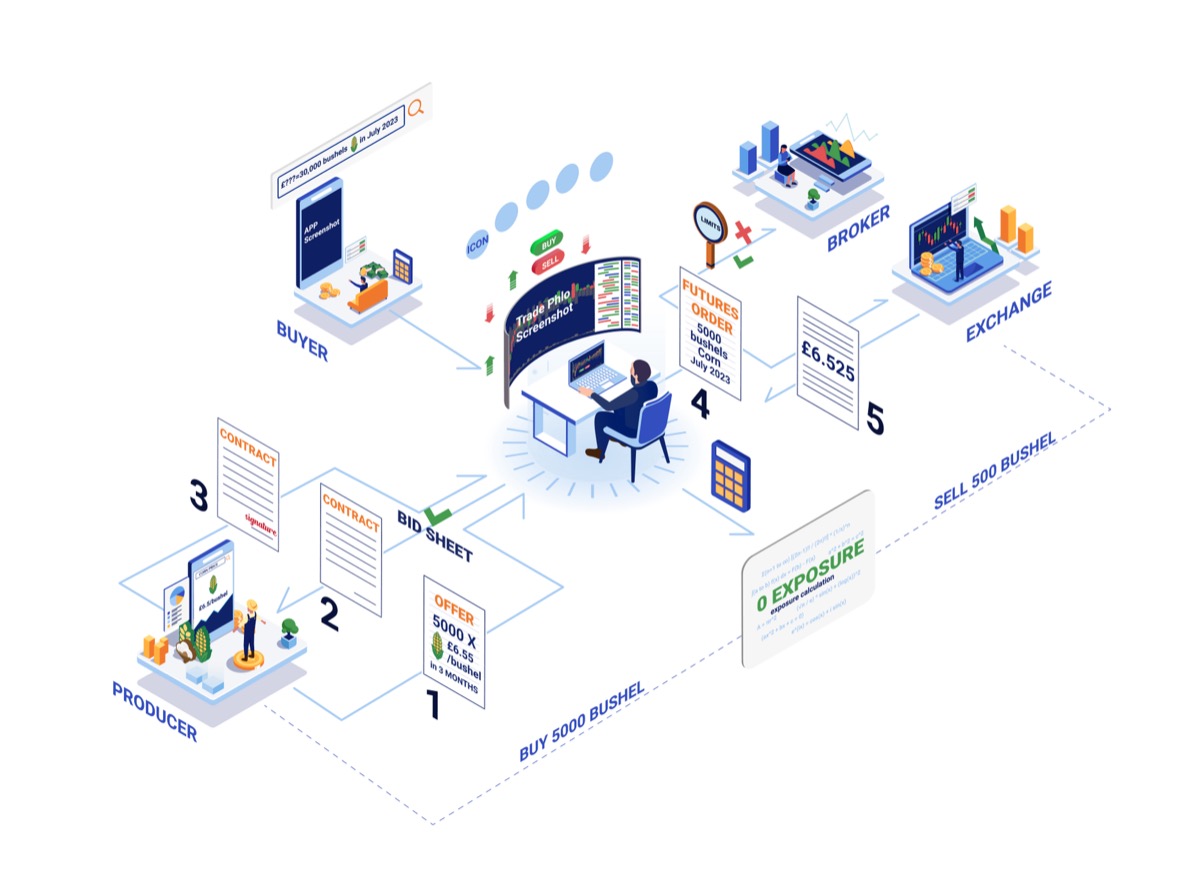
- Price fixation and un-fixed, basis contracts. A large share of physical commodity contracts are not priced at signing. A grain contract might be agreed at "December futures plus 20 cents" with the final price fixed later, within a window, at the buyer's or seller's option. An ERP inventory module has no native concept of a contract that is legally binding but not yet priced. It wants a unit cost at the moment of entry, which forces the trade onto a spreadsheet until someone remembers to fix it.
- Index and differential pricing. Many physical contracts price off a published index (an exchange settlement, a Platts or Argus assessment) plus or minus a differential for location, grade, or timing. That differential itself can be a negotiated, moving number. A generic inventory record has no field for "linked to this index, adjusted by this differential," so the link has to be maintained by hand, and it is exactly the kind of manual step that goes stale the week nobody has time to update it.
- Hedging and exposure by commodity. A trading book needs to see its open price exposure by commodity, delivery period, and often by currency, continuously, not as a monthly reconciliation exercise. That exposure has to net the physical position against the hedge, mark both to current market prices, and roll up into a risk figure a CFO can act on, such as value at risk. None of that exists in an inventory ledger designed to answer "how many units are in the warehouse."
- Grade and quality specifications. The same nominal commodity can trade at materially different values depending on protein content, moisture, purity, or grade, and a contract often allows for a quality adjustment against the agreed price if what arrives differs from what was ordered. A generic ERP's item master has a SKU and a description, not a quality specification that feeds into a price adjustment calculation.
- Laytime and freight. For bulk and break-bulk cargo, the time a vessel spends loading or discharging against an agreed allowance creates demurrage or despatch, a real cash amount that depends on shipping terms most inventory systems have never heard of. Freight terms also change who bears which cost and when title passes, which in turn changes when the position should actually hit the book.
- Letter of credit and documentary workability. Many cross-border physical trades settle against a letter of credit or similar documentary instrument, where payment depends on presenting the right set of compliant documents, not on an invoice being raised. An ERP built for domestic sales ledgers has no natural place to track documentary conditions, discrepancies, or presentation deadlines against the underlying trade.
Why this gap is becoming harder to ignore, not easier
For years, a trading firm outside oil, gas, and base metals could reasonably decide that commodity-specific software was a nice-to-have, because most of the CTRM and ETRM vendor market was built for and sold to energy and metals desks, and a softs or agricultural trader's workaround, a generic ERP plus a set of spreadsheets, was tolerable at smaller scale. That calculation is shifting. Competitive intelligence research tracking the CTRM and ETRM vendor landscape through 2026 shows established, generalist platforms actively expanding their functional coverage from their traditional energy and metals base outward into softs and agricultural commodities such as dairy and grain. When the vendors who built their businesses on energy and metals start investing in agri-specific functionality, that is a signal about where the market expects buyers to be, not just where those particular vendors want to sell next. Commodity-specific functionality is moving from a specialist feature to a baseline expectation across the board, agri and softs included, not only the energy and metals desks it originated with.
What this means for a CFO evaluating systems
- Ask what happens to an un-fixed contract. If the honest answer involves a spreadsheet tracking which lots still need a price fixed, the inventory module is not built for trading.
- Ask where exposure by commodity lives. If it is rebuilt periodically from several sources rather than read live from one book, the hedge a desk books today is already working from yesterday's picture.
- Ask whether quality and grade adjustments post automatically. A manual quality-adjustment journal entry at month end is a tell that the system treats the commodity as a generic SKU.
- Ask whether the same system understands laytime, freight terms, and documentary presentation, or whether those live in a logistics spreadsheet and a trade finance inbox that nobody has reconciled against the trading book this week.
Frequently Asked Questions
What is the main difference between a generic ERP inventory module and a commodity-aware CTRM?
A generic ERP inventory module tracks quantity and an average or standard cost per item, which assumes cost and value move together. A commodity-aware CTRM separates ownership of the physical goods from exposure to their price, and natively supports index and differential pricing, un-fixed contracts, quality and grade adjustments, and hedge exposure by commodity, none of which a standard inventory record is built to hold.
Why can't a trading firm just extend a generic ERP's inventory module to handle commodity pricing?
It can, in the same sense that a spreadsheet can be extended to track almost anything. The practical limit is that un-fixed pricing, index and differential links, and live hedge exposure all need to update continuously and feed each other, purchase to sale to hedge to general ledger, and a module designed around a static unit cost has no structural place for that chain to live without manual rework at every step.
Is commodity-specific functionality only relevant to energy and metals trading firms?
No, and that assumption is becoming less safe over time. Vendors whose products were originally built for energy and metals trading desks are actively extending their functional coverage into softs and agricultural commodities, which indicates the market increasingly expects commodity-specific functionality (price fixation, differential pricing, quality adjustments, hedge exposure) across agri and softs as well, not only the sectors the CTRM category originated in.
What should a CFO ask a vendor to test whether a system is genuinely commodity-aware?
Ask what happens, concretely, to a contract that is signed but not yet priced; ask where live exposure by commodity is calculated from; ask whether a quality or grade adjustment changes the contract value automatically; and ask whether laytime, freight terms, and letter of credit presentation are tracked in the same system as the trade itself. A vendor that answers all four from one data model is describing a commodity-aware CTRM. A vendor that answers any of them with "that's handled outside the system" is describing a generic ERP with a trading veneer.
How Phlo Systems helps
opsPhlo is built around the position, not the SKU. Un-fixed and basis contracts, index and differential pricing, grade and quality specifications, laytime and freight terms, and hedge exposure by commodity all live in the same data model as the purchase and sale contracts they relate to, so a price fixation or a quality adjustment updates the position and the general ledger together rather than requiring a separate reconciliation step. See how opsPhlo handles commodity-specific trading.
Related reading:
- What is the difference between Commodity Management (CM) and CTRM?
- Why SME commodity traders deserve an integrated ERP + CTRM + Treasury system
Saurabh Goyal is the Founder & CEO of Phlo Systems. He spent 12 years building CTRM and ERP systems for global commodity trading houses before founding Phlo in 2016.
Want to learn more about Phlo Systems?
See how our platform digitises international trade for commodity traders, importers, and exporters.
Get Started